
How to Measure the Real ROI of Marketing AI
The short answer
Judging marketing AI solely on top-line revenue leads to bad budget calls. Here is how to isolate true costs and verifiable returns.
When companies introduce AI into their marketing operations, the associated investments rarely appear on a single ledger.
Software subscription fees sit under IT procurement. External enablement, consulting, and workflow design fees end up categorized as professional services. Meanwhile, the internal hours spent testing prompts, troubleshooting workflows, and reviewing outputs are often never tracked at all.
By year-end, leadership can review total revenue and aggregate marketing spend, but they still cannot answer a fundamental question: What return did the marketing AI initiative actually generate?
Marketing AI adoption involves introducing AI software, content workflows, and hands-on enablement or custom development to reshape how teams work.
These initiatives can dramatically shift production turnaround, output volume, publishing frequency, and the marginal cost per asset. Over time, they can also influence customer acquisition and revenue.
However, top-line revenue is constantly pushed and pulled by seasonality, macro market conditions, and broader campaign spending. Crediting every bump in revenue to AI is bad math. Dismissing an AI rollout simply because overall top-line revenue remained flat is just as flawed.
To evaluate whether an initiative warrants continued funding, you must isolate its return on investment (ROI):
$$\text{ROI} = \frac{\text{Gains} - \text{Investment}}{\text{Investment}}$$
The formula is elementary. The difficulty lies in drawing clear accounting boundaries, capturing full costs, tying gains to auditable data, and separating single-period ROI from your overall payback horizon.
Draw Clear Boundaries: What Belongs to Marketing AI?
Before tracking any numbers, ask one baseline question:
Would this expense or operational shift have occurred if we had never launched our marketing AI initiative?
Base salaries for your existing content team and your legacy paid media budget would have been spent regardless. You cannot lump them into new AI investments. Your ledger should capture only the incremental costs and operational changes driven directly by the AI initiative:
- New subscriptions for AI tools, generation platforms, and supporting software
- Fees for external enablement, operational consulting, workflow design, and custom technical integrations
- Incremental increases or decreases in team labor hours due to workflow changes
- Internal time allocated to team training, prompt testing, and workflow iteration
Once your scope is defined, standardize your tracking window.
Monthly reviews introduce too much short-term noise. Waiting until an annual audit makes it impossible to disentangle AI impact from unrelated market changes. Evaluating numbers on a quarterly basis or across a complete content production cycle provides a far clearer comparison of inputs versus outputs.
Whichever timeframe you choose, keep your measurement criteria identical across periods. If your accounting baseline shifts mid-stream, your final numbers lose all comparative value.
True Costs Go Beyond SaaS Subscriptions
Treating tool subscriptions as the sole investment is the most common accounting error in AI initiatives. It creates an artificially inflated ROI, masking the operational investments the business actually made.
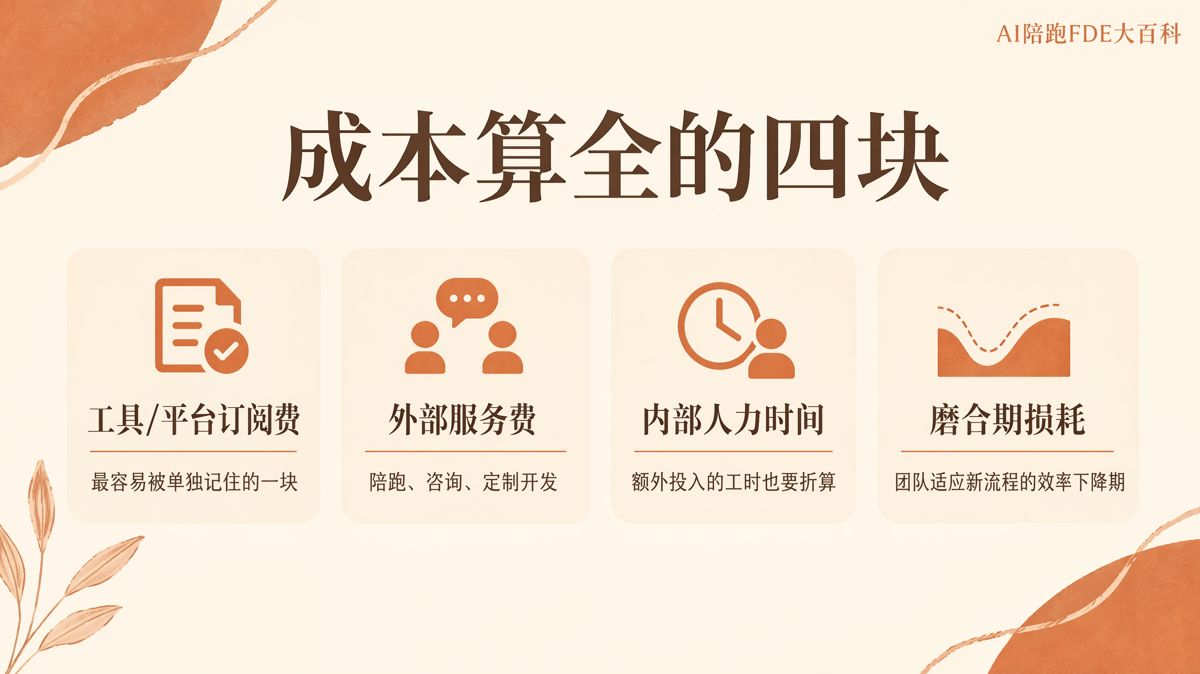
A complete cost model includes four distinct components:
1. Tool and Platform Fees
Direct recurring subscription costs or compute charges for AI engines, workflow automations, and supporting software.
2. External Enablement and Services
Contracted fees for hands-on operational consulting (such as FDE enablement), workflow architecture, and custom integrations.
3. Internal Labor Time
Existing employees already draw a base salary, but if adopting AI demands additional meetings, prompt engineering, editing cycles, and reviews, those incremental hours must be tracked and converted into monetary cost.
This measures the variance in working hours driven by AI adoption—not your department's entire baseline payroll.
4. Ramp-Up and Friction Costs
Transitioning from manual workflows to AI-assisted processes creates an initial productivity dip. Teams must test, make mistakes, and adjust their handoffs. That temporary drag on throughput represents real overhead that should be factored into your baseline.
Be careful not to double-count internal labor hours and ramp-up time. Define upfront which category captures testing and training hours, and keep those entries separate.
Rigorous cost accounting is not about inflating expenses. It is about creating audit-ready figures with clear boundaries that finance can independently verify.
Returns Must Rely on Auditable Operational Data
Qualitative feedback like "content output feels faster" or "the team loves the new setup" cannot support budget allocation. They lack standard baselines and cannot be balanced against financial inputs.
Track marketing AI performance across three verifiable metric categories:
| Metric Category | Trackable Data Points | Measurement Focus |
|---|---|---|
| Capacity | Production time per asset, output volume per unit of time, publishing frequency | Apply identical measurement criteria before and after adoption |
| Cost Structure | Marginal cost per additional content piece | Clearly identify which line items increased or decreased |
| Conversion | Attributable pipeline, inbound leads, or revenue tied directly to AI-assisted workflows | Never substitute aggregate company revenue |
Marginal cost represents the expense required to produce one additional unit of content. It is distinct from average cost across your entire department; keep the two concepts separate.
Capacity metrics demonstrate productivity shifts. However, raw hours saved or total pieces published cannot be dropped directly into an ROI equation. They must be translated into auditable financial value—such as reduced reliance on external freelance production or measurable operational savings—using standard financial criteria. Any efficiency that cannot be reliably converted into currency should be noted as an operational gain, not added directly to financial return figures.
Capacity and unit costs are generally straightforward to verify because turnaround times and operational expenses are tracked internally.
Conversion metrics require more rigor. Pipeline generation and deal closures are influenced by pricing, ad spend, product launches, and seasonal shifts. You cannot treat every dollar earned after an AI rollout as a direct return on that tool. Establish consistent control baselines or multi-stage attribution to isolate the AI workflow's contribution, and explicitly note any unresolved market variables in your final report.
Different metrics mature at different speeds. Internal efficiency indicators (production speed, asset volume, turnaround times) shift within weeks. Audience growth, organic search visibility, and downstream conversions require a complete content lifecycle to show reliable trends.
Vendor claims promising "results in 14 days" or "10x conversion boosts" are sales pitches, not performance baselines. Never substitute external benchmarks for your company's own verified data.
Separate Single-Period ROI from Payback Horizons
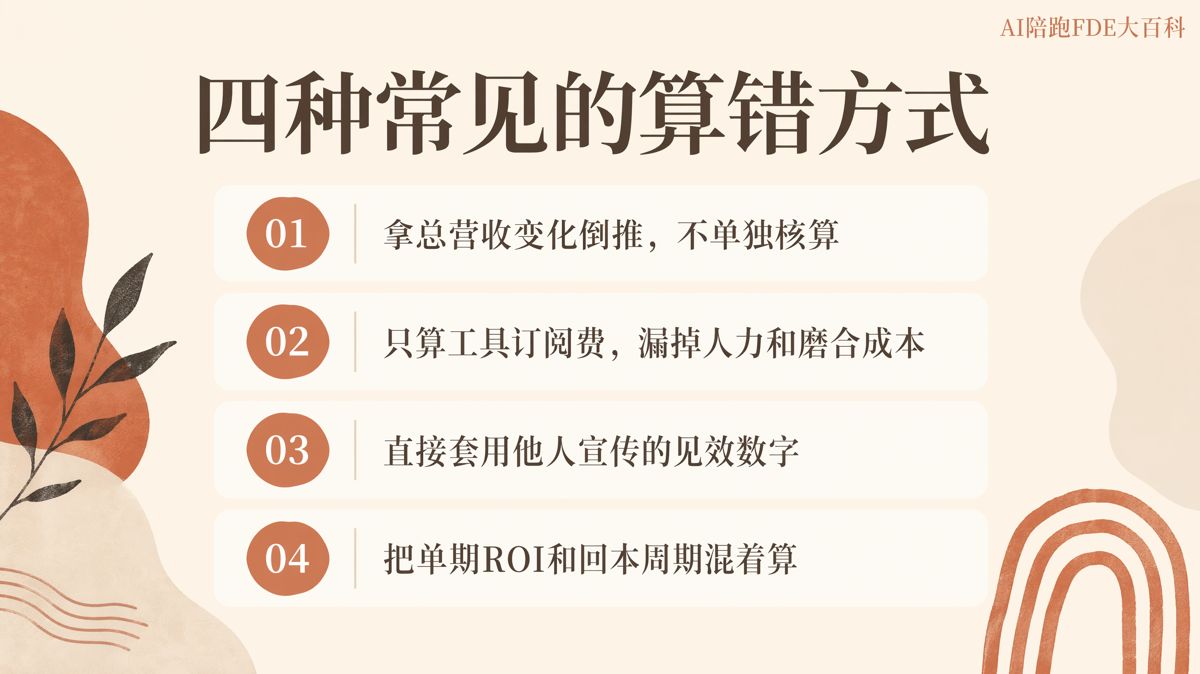
Single-period ROI and total payback timeline answer two different strategic questions.
Single-period ROI measures efficiency in a single window: During this specific quarter or production cycle, what was the ratio of net returns to costs incurred?
Payback horizon measures capital recovery: How long will it take for cumulative net returns to offset our total historical investment in this initiative?
A negative ROI in your first quarter does not mean the project failed. It often indicates that your team is still in the ramp-up phase, where initial consulting, tool setup, and training costs have not yet been offset by production efficiency.
Similarly, an unusually high ROI in a single quarter does not guarantee that rate is permanent. That quarter's return may reflect the compounded distribution of content built over earlier cycles. Always match returns to their appropriate operational window rather than mistaking cumulative momentum for single-period efficiency.
Budget allocation requires looking at both metrics side by side. Killing an initiative because of temporary ramp-up costs or doubling down based on a single quarter's spike are equally risky.
Four Questions to Review Before Finalizing Budgets
If your reporting includes any of the following assumptions, it is not ready for executive decision-making:
- Did you deduce AI returns simply by looking at shifts in total company revenue?
- Did you treat tool subscription pricing as your only investment cost?
- Did you substitute vendor marketing materials or third-party case studies for internal metrics?
- Are you judging the entire viability of the initiative based on one volatile quarter?
These questions address attribution integrity, cost completeness, data reliability, and evaluation horizons. If any of these four areas are unclear, your final ROI calculation is unreliable.
ROI Modeling Is Not Solely a Marketing Exercise
Marketing teams understand workflow mechanics best. They should define project boundaries and supply source logs for capacity, marginal cost shifts, and pipeline attribution.
Finance must verify that all cost categories are accounted for, confirm that tracking windows are sound, and validate that return figures are verifiable.
Leadership then uses these verified numbers to make an informed capital decision: scale the investment, refine the workflow, or pull the plug.
A decision-grade marketing AI evaluation should clearly present:
- Exactly which expenses were included and excluded
- The designated evaluation window
- Line-item expenditures alongside their calculation methods
- How return metrics were documented and audited
- Current single-period ROI
- Progress toward the full payback break-even point
- Confounding external variables that could not be fully isolated
Once this data is auditable, marketing AI spending ceases to be an opaque line item buried inside general marketing overhead.
Leadership can move past abstract arguments about whether "AI works" and focus on strategic business realities: what the investment actually delivered, whether it met operational targets, and where to allocate next quarter's budget.
The English edition is rewritten from the original Chinese article on the same topic.

Starbox AI is an AI marketing company based in Hangzhou, China. This article draws on Starbox project work. Please credit the source when quoting.
Related reading
 AI Adoption
Can One AI Operator Really Replace 10 People?
Claims of 10x headcount cuts count generation speed, not QA and rework. Real efficiency measures net pipeline hours saved.
Oct 22, 2026 · 6 min read
 AI Adoption
Bought Basic AI and Seeing Zero ROI? A 4-Step Activation Playbook
Activating entry-level AI is not about model parameters. Turn open chat boxes into defined operational stations with clear inputs, templates, and QA checklists.
Oct 22, 2026 · 6 min read
 AI Adoption
Why One-Click AI Fails at Work: How to Pick Enterprise Agents
One-click AI tools seem easy, but their first-draft accuracy is terrible. Real business ROI requires multi-step workflows with your own knowledge base.
Oct 21, 2026 · 6 min read